 Wael.T
A deep 2026 guide to allocating €20,000 in France across emergency savings, Livret A, LEP, LDDS, term deposits, a house deposit and long-term PEA/ETF…
Updated: August 26, 2026
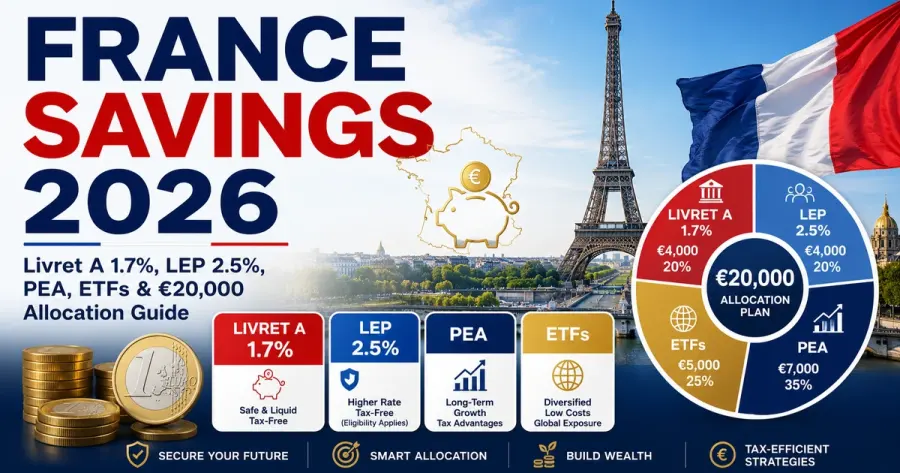
France’s savings landscape changed again on 1 August 2026: Livret A and LDDS now pay 1.7%, while the income-tested LEP remains at 2.5%. At the same time, INSEE reported July consumer-price inflation of 2.1% year over year. The useful question is not whether cash or equities are universally better. It is what job each euro has to do. Money needed next month, a home deposit needed in two years and retirement capital for twenty years should not be put in the same place.
The most useful 2026 question is not “what pays the highest rate?”
A saver with €20,000 can receive radically different advice depending on the purpose of the money. If the entire amount is the household's only emergency reserve, protecting capital and maintaining immediate access are more important than maximizing return. If €20,000 is a home deposit that will be needed in 18 months, stock-market volatility can create a timing problem. If the same money is genuinely surplus capital for 15 years, leaving all of it in cash can create a different risk: lost purchasing power and lost compounding.
France's 2026 environment makes that distinction visible. From 1 August, the government set Livret A and LDDS at 1.7% and maintained the LEP at 2.5% for eligible households. INSEE's headline consumer-price measure was 2.1% year over year in July. Those figures are not perfectly comparable because regulated-savings formulas use different inflation concepts and averaging periods. Cash should therefore be judged first by safety, liquidity, tax treatment and purpose.
Start by dividing €20,000 into time-horizon buckets
A practical framework is to label money by when it may be spent. The first bucket is immediate: bills, emergencies and expenses that may occur within roughly a year. The second is medium term: a home deposit, car, education expense or business project in perhaps one to five years. The third is long term: retirement, financial independence or wealth that can remain invested through a severe bear market.
Use the Savings Goal Calculator to attach a date and required amount to each goal. If €20,000 contains €8,000 of emergency money, €7,000 for a home purchase and €5,000 with no planned use for a decade, treating the full €20,000 as one “investment portfolio” destroys useful information.
Emergency money: liquidity is a feature, not an investment failure
Emergency savings need to be available on the day a boiler fails, a car breaks down or income stops. A volatile ETF that happens to be down 25% at that moment is a poor emergency asset even if its expected 15-year return is higher. The goal is not to win a return contest; it is to prevent a temporary household problem from becoming expensive debt.
Estimate the reserve with the Emergency Fund Calculator. A household with two stable incomes and low fixed expenses may need less cash than a self-employed household with irregular income, children and a large mortgage. A reserve should reflect job stability, insurance deductibles and essential spending.
If you qualify for LEP, its 2.5% rate deserves first attention for cash
The Livret d'épargne populaire is reserved for eligible households based on tax residence and income criteria. From 1 August 2026 its rate remains 2.5%, above the 1.7% Livret A and LDDS rate. Its interest is exempt from French income tax and social contributions under the regulated-savings framework, while the funds remain accessible.
Eligibility matters more than marketing. Do not build a plan around LEP unless your revenu fiscal de référence and household situation meet the current official thresholds. If you qualify, it can be a particularly attractive home for the part of emergency or short-term cash that fits within its rules.
Livret A remains a strong default for accessible tax-free cash
Livret A pays 1.7% from 1 August 2026 and allows up to €22,950 of deposits for an individual, excluding capitalised interest. Funds remain accessible and interest is exempt from income tax and social contributions. That combination makes the account useful for emergency reserves and short-term goals where certainty of principal matters more than market upside.
The deposit ceiling is not a target. A young renter with low fixed costs may not need €22,950 of emergency cash simply because the account permits it. A homeowner with variable income and dependants may sensibly need more liquid savings than a single Livret A can hold.
LDDS adds another €12,000 of regulated capacity
The Livret de développement durable et solidaire is aligned with Livret A and pays 1.7% from August 2026. Its deposit ceiling is €12,000, excluding accumulated interest. For eligible French tax residents it can therefore extend the household's regulated, liquid and tax-efficient cash capacity.
From a planning perspective LDDS is economically similar to Livret A: rate, liquidity, tax treatment and ceiling are the decisive variables. There is little reason to leave large sums in a near-zero current account without checking whether regulated accounts still have unused capacity.
Do not compare tax-free 1.7% with taxable 2.3% without calculating the net return
Banque de France data show that rates on new household term deposits can differ from average deposit rates and may sometimes exceed regulated-account headline rates. A taxable term deposit at 2.3% gross may look superior to Livret A at 1.7%, but the result depends on taxation, holding period, withdrawal restrictions and whether the quoted rate actually applies to your balance.
For short-term money, compare net euros received after tax and fees, not only the gross percentage. A six- or twelve-month term deposit can be suitable for money with a known date, but it may be unsuitable for an emergency reserve if early withdrawal is restricted or penalised.
Inflation should change the role of cash, not push emergency savings into equities
INSEE reported headline inflation of 2.1% year over year in July 2026. It is tempting to compare 2.1% directly with Livret A's 1.7% and conclude that cash is automatically “losing 0.4%.” That is too simplistic: the inflation measures and periods used in regulated-savings formulas differ from a single monthly headline figure, and every household has its own spending basket.
The broader lesson is that cash is designed to preserve nominal capital and liquidity, not necessarily to maximize long-term real return. Once emergency and medium-term buckets are adequately funded, long-horizon money deserves a separate investment decision rather than remaining in cash indefinitely out of habit.
France's high household saving rate makes allocation as important as saving more
Banque de France reported that the household financial saving rate rose to 9.5% in the first quarter of 2026. French households are not generally unfamiliar with saving. The challenge for many is deciding how much accumulated cash should stay liquid and how much can move toward longer-term assets.
A household with €80,000 in cash but only €15,000 of annual essential expenses may have more liquidity than its risk profile requires. Another household with the same €80,000 and an imminent property purchase may have exactly the right amount. Asset allocation without goals is guesswork.
House deposit in one to three years: protect the date, not the theoretical return
If €20,000 is intended as apport personnel for a home purchase in 2027 or 2028, the investment horizon is short. A global equity ETF can decline 20%, 30% or more during a bad market and may not recover before the notary needs the funds. Long-term historical equity returns do not remove short-term sequencing risk.
Use the Down Payment Calculator and Savings Goal Calculator to determine the deposit amount and monthly contribution. For a dated goal, regulated savings and appropriate term deposits can be more suitable than shares even if the expected return is lower.
Mortgage rates also affect how much deposit you need
Banque de France reported an average rate of 3.21% on new housing loans excluding renegotiations in May 2026, before certain fees and insurance in the measure used. Individual borrowers can receive different rates based on profile, term, contribution and bank. The relevant planning issue is that a larger deposit can reduce the amount borrowed and improve affordability.
Use the Home Affordability Calculator to test property price, deposit and monthly debt burden before deciding how much of the €20,000 is truly long-term. A near-term house deposit should not depend on an equity-market recovery.
Renting versus buying should be modelled before locking all cash into a deposit
French homeownership decisions include transaction costs, notary fees, property tax, maintenance, financing and the opportunity cost of the deposit. A higher deposit reduces borrowing but also removes liquidity that could remain available for emergencies or investment.
The Rent vs. Buy Calculator can structure the comparison. Use realistic assumptions for rent growth, mortgage rate, maintenance, time in the property and investment return. Buying can be financially sound without being universally superior over a short holding period.
For money you can leave for 10+ years, the PEA deserves attention
The Plan d'épargne en actions is a French tax wrapper designed for long-term equity investing. The AMF explains that a standard PEA has a €150,000 contribution ceiling and, after five years, gains and dividends can benefit from income-tax exemption while social contributions still apply. The wrapper changes taxation; it does not guarantee investment returns.
The time horizon therefore comes before the tax wrapper. If the money may be needed for a home purchase in three years, the five-year milestone does not make equities a safe three-year asset. If the goal is retirement in twenty years, the PEA structure can be much more relevant.
PEA eligibility is not the same as “only buy French stocks”
PEA rules restrict the securities that can be held directly and the eligibility of funds, but eligible collective funds and ETFs can provide diversified exposure under the rules. Check the product's official eligibility and DIC rather than assuming every global ETF listed by a broker can sit inside a PEA.
Do not build a concentrated CAC 40 portfolio merely because the account is French. The objective is tax-efficient investing within the legal universe, not home-country concentration. Diversification across companies, sectors and geographies remains important.
ETFs can reduce fund costs, but “cheap” is not “safe”
The AMF's 2026 ETF guidance notes that ETFs seek to track an index and can offer diversification in one transaction. ETF fees are often below 0.5% a year, whereas actively managed funds can exceed 1% or 1.5% in some categories. That cost gap can matter over decades.
An ETF can still lose substantial value because the underlying market falls. Tracking error, liquidity, currency exposure and index concentration can also matter. Read the DIC and avoid treating a leveraged or narrow thematic ETF as if it were automatically diversified.
PEA fees vary sharply by provider
The AMF's 2026 fee work found meaningful differences between traditional network banks, online banks and newer brokers. For a €1,000 internet order, the average brokerage fee in the network-bank PEA sample was around 0.49%, while some online providers were materially cheaper. Custody and account fees may also matter.
Use the Investment Calculator to model 0.2%, 0.5% and 1.0% annual total-cost differences over twenty years. Fee differences that look small in a tariff brochure can compound into thousands of euros.
Lump sum versus monthly investing: distinguish risk capacity from market prediction
If the €20,000 is already available and genuinely long term, investing immediately gives the capital more time in the market but exposes the full amount to an immediate downturn. Phasing the investment over six or twelve months can reduce the emotional impact of unlucky timing but leaves some cash uninvested for longer.
There is no universal behavioural answer. An investor who knows a 25% drop immediately after investing would trigger panic selling may prefer a staged plan even if immediate investment offers more time in market. The best plan is one that can actually be followed through volatility.
Use monthly contributions to reduce the importance of today's valuation
Once the initial allocation is set, regular contributions reduce the importance of deciding whether August 2026 is the “right” month to buy. A fixed monthly amount creates process discipline without requiring a forecast. More units are bought at lower prices and fewer at higher prices.
The Compound Interest Calculator can show how €250 or €500 monthly contributions compare with the initial €20,000. Over long periods, the savings rate can matter more than small differences in entry price.
Example 1: €20,000 is your entire liquid net worth
Assume essential household expenses are €2,000 per month and employment is moderately stable. Placing all €20,000 into a PEA may leave no cash for an emergency. A more resilient approach could keep a substantial emergency bucket in LEP if eligible and/or Livret A, with only the genuine long-term surplus invested.
If the emergency target is €12,000, only €8,000 is currently available for medium- or long-term goals. Future savings can then rebuild flexibility and increase the invested share without weakening the safety layer.
Example 2: €20,000 is a house deposit for 2028
Here the date dominates. The saver may use Livret A, LEP if eligible, LDDS and selected term deposits rather than equities. If €20,000 needs to become €30,000 in twenty-four months, the main driver will be the additional €10,000 of contributions, not an attempt to earn a speculative double-digit return without risk.
The Savings Goal Calculator translates that gap into a monthly amount. If the required contribution is unrealistic, a later purchase date, lower property budget or higher household savings rate is more robust than simply taking more market risk.
Example 3: €20,000 is surplus capital for fifteen years
A saver already holding a complete emergency reserve and no near-term claim on the money can consider a PEA and diversified eligible equity ETFs, subject to risk tolerance. The portfolio can still fall sharply. A fifteen-year horizon creates recovery time but does not guarantee a positive outcome on a specific date.
Use the Investment Calculator with several return assumptions rather than one optimistic number. A 4%, 6% and 8% scenario shows sensitivity without pretending any of them is promised. Add ongoing monthly contributions to see how behaviour affects the result.
Example 4: €50,000 of savings with three goals
Suppose a household has €50,000, needs €15,000 as emergency liquidity, expects €20,000 for a home project in three years and can invest €15,000 for retirement. The logical result is three portfolios: safe liquid savings, low-risk dated savings and long-term investments. The household does not need to choose between “Livret A or PEA” for the entire €50,000.
This bucket method makes later changes easier. When the home project is completed, future contributions can shift toward long-term investing. When the emergency reserve is used, new savings rebuild it before additional market risk is added.
High-cost consumer debt can outrank both Livret A and PEA
Banque de France reported an average rate of 6.53% on new amortising consumer loans in May 2026, while individual revolving and personal-credit rates can be higher. A household paying materially more than safe savings earn may improve its balance sheet by repaying debt instead of accumulating excess cash investments.
Use the Loan Calculator to calculate remaining interest. A low-rate mortgage is a more nuanced trade-off because the guaranteed saving from repayment is smaller. Compare after-tax, risk-adjusted alternatives rather than relying on slogans.
Do not confuse PEA tax benefits with guaranteed tax simplicity
PEA rules around withdrawals, eligibility and tax treatment depend on the age of the plan and current law. The five-year milestone is important, but account operations still need to follow the rules. Fund structures and changing regulation can add details.
Keep records and rely on current official AMF and tax guidance for material decisions. A financial calculator can model growth but cannot determine your personal French tax liability.
Review the cash-versus-investment split when life changes
A portfolio that was suitable for a single renter can become wrong after a home purchase, child, career break or business launch. The emergency target can rise, the home-deposit bucket can disappear, and long-term risk capacity can change.
A useful review happens after major life events and at least annually. You do not need to move money because a newspaper headline changes each week. Rebalancing should follow goals, horizon and risk capacity.
A 2026 decision tree for the next euro
If the euro is needed within months, prioritise accessibility and capital protection. If it belongs to emergency reserves, LEP for eligible savers and Livret A or LDDS are natural products to investigate. If it has a fixed one-to-three-year purpose, consider safe savings and term deposits that mature before the goal date. If it can stay invested for a decade or more, a PEA with diversified eligible funds can enter the conversation.
If you are simultaneously carrying expensive consumer debt, compare that interest cost before adding surplus investments. If your emergency reserve is incomplete, finish the resilience layer before maximizing market exposure. This decision tree is more durable than a yearly list of “top five accounts.”
Bottom line: give every euro a job before choosing the account
The 2026 French savings market offers useful tools at each horizon. LEP's 2.5% can be particularly attractive for eligible cash savers; Livret A and LDDS at 1.7% remain highly liquid and tax-free; term deposits can compete for money with a known date; and the PEA can provide a tax-efficient framework for genuinely long-term eligible equity investing. None is the universal winner.
Start with emergency resilience, then fund dated goals, then invest the long-term surplus. Use the Savings Goal, Emergency Fund, Down Payment, Investment and Compound Interest calculators to quantify each bucket. This article is general educational information and not personalised investment, tax or financial advice.
Authoritative sources
- French Ministry of Economy — Livret A
- French Ministry of Economy — regulated savings rates from 1 August 2026
- French Ministry of Economy — LEP
- French Ministry of Economy — LDDS
- Banque de France — household saving Q1 2026
- Banque de France — deposit remuneration June 2026
- Banque de France — household housing credit May 2026
- AMF — PEA guide
- AMF — ETF guide
- INSEE — consumer prices