 Wael.T
A deep 2026 Canadian first-home guide covering the $8,000 FHSA room, $40,000 lifetime limit, $60,000 Home Buyers’ Plan, $7,000 TFSA limit, new-home GST/HST…
Updated: August 26, 2026
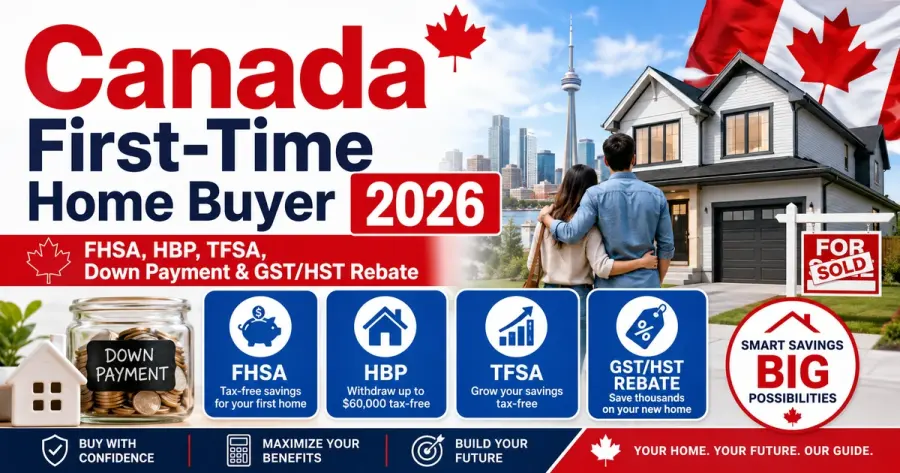
Canada’s first-home toolkit is unusually powerful in 2026. A qualifying buyer can use an FHSA with an $8,000 first-year contribution room and $40,000 lifetime contribution limit, combine a qualifying FHSA withdrawal with up to $60,000 from an RRSP under the Home Buyers’ Plan, use TFSA savings without tax on the withdrawal, and—when buying an eligible newly built home—potentially claim the new first-time home buyers’ GST/HST rebate. The challenge is sequencing these tools without draining emergency cash, over-contributing to registered accounts or buying a home that only works on paper.
Why the 2026 first-home plan starts with cash flow, not a tax account
Registered plans can improve the path to a down payment, but they cannot make an unaffordable property affordable. Begin with the home price you can carry after mortgage payments, property tax, utilities, condominium fees where applicable, insurance, maintenance and normal living costs. Use the Home Affordability Calculator before deciding how much to move into an FHSA or RRSP. A buyer who can technically assemble a $70,000 down payment but has no room for a $4,000 monthly housing budget has solved the wrong problem.
Know the federal minimum down-payment rules before setting your target
The Financial Consumer Agency of Canada explains that the minimum down payment is generally 5% on a purchase price of $500,000 or less; for homes above $500,000 and below $1.5 million, it is 5% of the first $500,000 plus 10% of the portion above $500,000; at $1.5 million or more, the minimum is 20%. A lender can require more based on the file. Use the Down Payment Calculator to convert a target purchase price into a minimum, 10%, 15% and 20% scenario rather than relying on a round number.
A 20% down payment is a financing threshold, not a universal goal
Putting at least 20% down usually avoids mortgage default insurance, but waiting to reach 20% can take years in an expensive market. A smaller insured down payment may let a household buy sooner, while a larger down payment reduces the mortgage balance and monthly payment. The trade-off depends on rent, home-price risk, income growth, the cost of insurance and how much liquidity remains after closing. Do not empty every account simply to hit 20%; ownership becomes fragile if the first repair has to go onto a credit card.
The FHSA is the first registered account many eligible buyers should understand
The First Home Savings Account combines characteristics of an RRSP and a TFSA: eligible contributions are generally deductible, investment growth can occur inside the plan, and a qualifying withdrawal to buy or build a first home is not taxable. Your participation room in the year you open your first FHSA starts at $8,000, while the ordinary lifetime FHSA contribution limit is $40,000. The account therefore offers both an immediate tax-planning benefit and a tax-free home-purchase exit when the conditions are satisfied.
Opening the FHSA earlier can be more valuable than contributing later
FHSA room does not begin accumulating merely because you are an adult. The participation period begins when you open your first FHSA. Unused participation room that can be carried to a later year is generally capped, so someone who expects to buy in several years may benefit from opening an account before they are ready to contribute the full $8,000. A person who opens in 2025 and contributes nothing can, subject to the rules, have up to $16,000 of participation room in 2026; someone who waits until 2026 to open starts with $8,000.
FHSA carry-forward is useful, but it is not unlimited
CRA’s calculation rules distinguish participation room, carry-forward, excess amounts and certain re-participation amounts. The ordinary carry-forward of unused participation room is limited to the lesser of $8,000 and the calculated unused amount. That means you cannot wait five years and suddenly contribute $40,000 simply because the lifetime limit is $40,000. Check your current FHSA participation-room statement in CRA My Account or your Notice of Assessment before making a large contribution, especially if you have transferred money from an RRSP.
The FHSA deduction can be saved for a future higher-income year
Contributing and claiming the deduction are related but not identical decisions. CRA allows unused deductible FHSA contributions to be carried forward, so a worker who contributes while earning a modest income may choose to claim some or all of the deduction in a later year with a higher marginal tax rate. Unlike RRSP contributions made in the first 60 days of a calendar year, an FHSA contribution made in January or February 2026 cannot be deducted on the 2025 tax return. The FHSA contribution period follows the calendar year.
The investment inside the FHSA should match the purchase date
An FHSA is an account wrapper, not an investment by itself. If the home purchase may occur in twelve months, an equity ETF can create a severe timing risk: a 25% market decline could remove one quarter of the planned down payment just before closing. Cash, high-interest savings products, GICs that mature before the purchase or other low-volatility holdings may fit a near-term FHSA better. For a buyer five or more years away, some investment risk may be acceptable, but the allocation should become more conservative as the purchase becomes real.
The Home Buyers’ Plan can add up to $60,000 per participant from an RRSP
The federal Home Buyers’ Plan currently allows an eligible participant to withdraw up to $60,000 from RRSPs to buy or build a qualifying home. The withdrawal is not treated like an ordinary taxable RRSP withdrawal when HBP conditions are met, but unlike an FHSA qualifying withdrawal, the HBP creates a repayment obligation. This distinction matters. The HBP is effectively borrowing from your own retirement account; the FHSA is designed to provide a tax-free qualifying home withdrawal without repayment.
A 2026 HBP withdrawal receives unusually long repayment relief
CRA states that temporary repayment relief has been extended for people whose first HBP withdrawal occurs from 2026 through 2028. Instead of beginning the standard 15-year repayment period in the second year after withdrawal, these participants receive an additional three-year deferral. For a first withdrawal in 2026, the first repayment year is 2031. That improves early homeowner cash flow, but it does not erase the eventual obligation to restore the scheduled amount to retirement savings or include a shortfall in income under the applicable HBP rules.
FHSA and HBP can be used for the same qualifying home
One of the most useful current rules is that a buyer can make a qualifying FHSA withdrawal and an HBP withdrawal for the same home if all conditions are met at each withdrawal. A couple who each has $40,000 accumulated in an FHSA and $60,000 available through the HBP could theoretically assemble a very large registered-plan contribution to the purchase. In practice, using the maximum from every account may not be wise if it destroys retirement diversification or leaves the household with no accessible reserve after closing.
Do not transfer RRSP money to an FHSA merely to create another tax deduction
Direct transfers from an RRSP to an FHSA can use FHSA participation room, but the transfer is not an additional deductible FHSA contribution. The tax deduction generally arose when the original RRSP contribution was made. A transfer may still be strategically useful because a future qualifying FHSA withdrawal does not need to be repaid like an HBP withdrawal. However, it also uses part of the FHSA’s lifetime participation limit. Compare the value of converting RRSP dollars into FHSA dollars with simply making new deductible FHSA contributions from cash.
The TFSA remains the most flexible down-payment account
The 2026 TFSA dollar limit is $7,000, with additional contribution room potentially available from prior eligible years and previous withdrawals. TFSA contributions are not deductible, but investment income and withdrawals are generally tax-free. For a home buyer, the TFSA’s main advantage is flexibility: withdrawing for a down payment does not create an HBP repayment schedule, and the withdrawn amount is generally added back to TFSA contribution room in the following calendar year under the normal rules.
TFSA over-contribution mistakes often happen after withdrawals
Do not assume that money withdrawn from a TFSA can be recontributed immediately in the same year unless you already have unused room. The amount withdrawn normally returns as room on January 1 of the following year. CRA recommends checking personal records because financial-institution reporting can lag. If you withdraw $25,000 for a home and then receive money from family later that year, recontributing the $25,000 immediately may create an excess if you do not have separate unused room.
The new first-time home buyers’ GST/HST rebate is a major 2026 new-build factor
After Royal Assent in March 2026, applications opened for the federal first-time home buyers’ GST/HST rebate. Eligible first-time buyers of qualifying newly built or substantially renovated homes can receive up to 100% of the GST or federal portion of HST on a home valued at $1 million or less, up to a maximum federal rebate of $50,000. The rebate phases down between $1 million and $1.5 million and is unavailable at $1.5 million or above. Purchase-agreement and construction dates must also satisfy the detailed rules.
Do not count the GST/HST rebate as cash until you understand how your purchase is structured
The rebate can materially change the economics of a new build, but builder pricing, whether tax is included in the advertised price, assignment arrangements, provincial HST components and application mechanics matter. Ontario now has an additional first-time home buyers’ rebate for the provincial HST component under its own conditions. A buyer should ask the builder and lawyer exactly how the rebate is reflected at closing rather than simply subtracting $50,000 from the listing price in a personal spreadsheet.
Thirty-year insured amortization lowers the payment but usually raises total interest
Since December 2024, 30-year amortizations for insured mortgages have been available to all first-time home buyers and to all buyers of new builds under the federal reforms, subject to mortgage-insurance rules. Stretching repayment from 25 to 30 years can lower the monthly payment and help a borrower qualify, but it also keeps principal outstanding longer. Use the Amortization Calculator to compare the same mortgage at 25 and 30 years and calculate the extra lifetime interest if rates were unchanged.
A lower monthly payment is not the same as a lower-cost home
A 30-year amortization can create room in the monthly budget, which may be valuable for a young household with childcare costs or early-career income. The danger is using the lower payment to justify a substantially more expensive property. A buyer who could afford a $650,000 home on 25 years should not automatically raise the budget to $725,000 simply because 30 years makes the payment fit. Use the longer term as a flexibility tool, not as permission to eliminate every margin of safety.
Model mortgage insurance as part of the financed balance
When the down payment is below 20%, mortgage loan insurance is typically required, subject to federal and insurer rules. The premium is commonly added to the mortgage principal, which means interest can be paid on it for years. Compare a 10%, 15% and 20% down-payment scenario using the Mortgage Calculator. The 20% option saves insurance but may require years of extra saving; the lower-down-payment option preserves time and potentially liquidity but increases the financed amount.
Remember closing costs that are not part of the down payment
Land transfer taxes where applicable, legal fees, title insurance, inspections, appraisal charges, moving costs, utility adjustments, property-tax adjustments and immediate repairs can require cash at or shortly after closing. Some cities and provinces have first-time-buyer relief programs, but rules differ. A robust target is therefore “down payment plus closing reserve plus emergency reserve,” not merely “minimum down payment.” Keeping an extra 1.5% to 4% of purchase price available as a planning range may be prudent in some cases, but obtain local estimates instead of treating that range as a legal requirement.
Couples should coordinate registered accounts instead of saving randomly
If both partners qualify for FHSAs, each person has their own participation room and lifetime limit. Each may also have an HBP entitlement if the conditions are met. The most tax-efficient contribution order may differ because one partner can be in a higher marginal tax bracket, one may have more RRSP assets and the other may have more TFSA room. A shared spreadsheet should track whose account holds each dollar, what deduction is expected and what repayment obligation will exist after closing.
Example: a couple targeting a $700,000 home
Under the federal minimum formula, a $700,000 home requires at least $45,000 down: 5% of the first $500,000 is $25,000, plus 10% of the remaining $200,000 is $20,000. Suppose the couple has $30,000 across FHSAs, $25,000 of TFSA cash and $35,000 available through one HBP. They do not need to use all $90,000 merely because it exists. The better question is how much down payment improves the mortgage while preserving perhaps $15,000–$25,000 of post-closing cash for their actual household risk.
Example: a new-build buyer should model the rebate separately from financing
Consider an eligible newly built home at $900,000. The federal first-time-buyer GST/HST rebate can potentially be worth up to $50,000, but the exact cash-flow treatment depends on the transaction. Model the mortgage first using the actual contract price and required down payment, then create a second scenario reflecting the confirmed rebate mechanics. Do not use an unverified rebate assumption to stretch affordability. The home should remain viable if legal timing or builder administration delays the cash benefit.
Down-payment money should become safer as the purchase approaches
A buyer planning to purchase in five years can tolerate more uncertainty than someone making offers next month. As the target date approaches, shift the portion required for closing away from volatile assets. This is not an attempt to predict the stock market; it is matching the asset to a known liability. A 40% equity allocation might be reasonable for a flexible five-year goal for one household and completely inappropriate for a firm twelve-month purchase for another.
Debt-service capacity matters as much as the registered-account balance
Canadian mortgage lenders use gross and total debt-service measures rather than a single consumer “DTI” percentage, and underwriting also considers qualifying rates, income and property details. Still, the Debt-to-Income Ratio Calculator can be a useful household screening tool. Paying off a $700 monthly auto loan before buying may improve cash flow more than adding the same lump sum to the down payment, depending on the remaining loan balance and lender treatment.
Build the monthly saving plan backward from the closing date
If the target reserve is $80,000 and you have $48,000 today, the gap is $32,000. Over 24 months, that is roughly $1,333 a month before investment returns. The Savings Goal Calculator shows whether the target is realistic without assuming high market returns. When the required monthly contribution is impossible, the honest options are a later purchase, a lower price target, a larger household income or a different housing strategy—not a riskier down-payment portfolio.
Keep a post-closing emergency fund outside the home
Homeownership creates expenses that renters can pass to a landlord. Appliances fail, roofs leak, deductibles are due and property-tax bills can change. The Emergency Fund Calculator should be run again using the future homeowner budget, not the current renter budget. Money inside the home is not an emergency account unless you are willing and able to borrow against it later, which may be difficult precisely when household income is under stress.
A practical 2026 contribution order for many first-time buyers
One workable sequence is: determine the affordable home budget; establish a minimum emergency reserve; open and fund an FHSA when eligible; capture any valuable employer retirement match before redirecting RRSP savings; decide how much additional down-payment cash belongs in a TFSA or safe non-registered account; then evaluate HBP withdrawals closer to the purchase. New-build buyers should separately verify GST/HST rebate eligibility. This order is not universal, but it prevents the tax accounts from driving the home price.
Bottom line: combine the programs, but do not let the programs choose the house
Canada’s 2026 first-buyer system can materially improve a purchase: FHSA deductions and qualifying tax-free withdrawals, a $60,000 HBP limit, $7,000 of new annual TFSA room, the new GST/HST rebate for eligible new homes and access to 30-year insured amortization all create planning flexibility. The best outcome still comes from buying within a durable budget, keeping liquidity after closing and treating HBP money as retirement capital that must eventually be restored.
Use the Down Payment, Home Affordability, Mortgage, Amortization, Savings Goal and Emergency Fund calculators with your actual numbers and verify current CRA, lender, insurer, provincial and legal rules before acting. This article is educational information, not personalised tax, mortgage, legal or investment advice.
Authoritative sources
- CRA — First Home Savings Account (FHSA)
- CRA — FHSA contributions and participation room
- CRA — Home Buyers’ Plan
- CRA — 2026 TFSA contribution room
- FCAC — How much you need for a down payment
- FCAC — Buying a home
- Department of Finance Canada — 30-year amortization and insured-mortgage reforms
- CRA — First-time home buyers’ GST/HST rebate